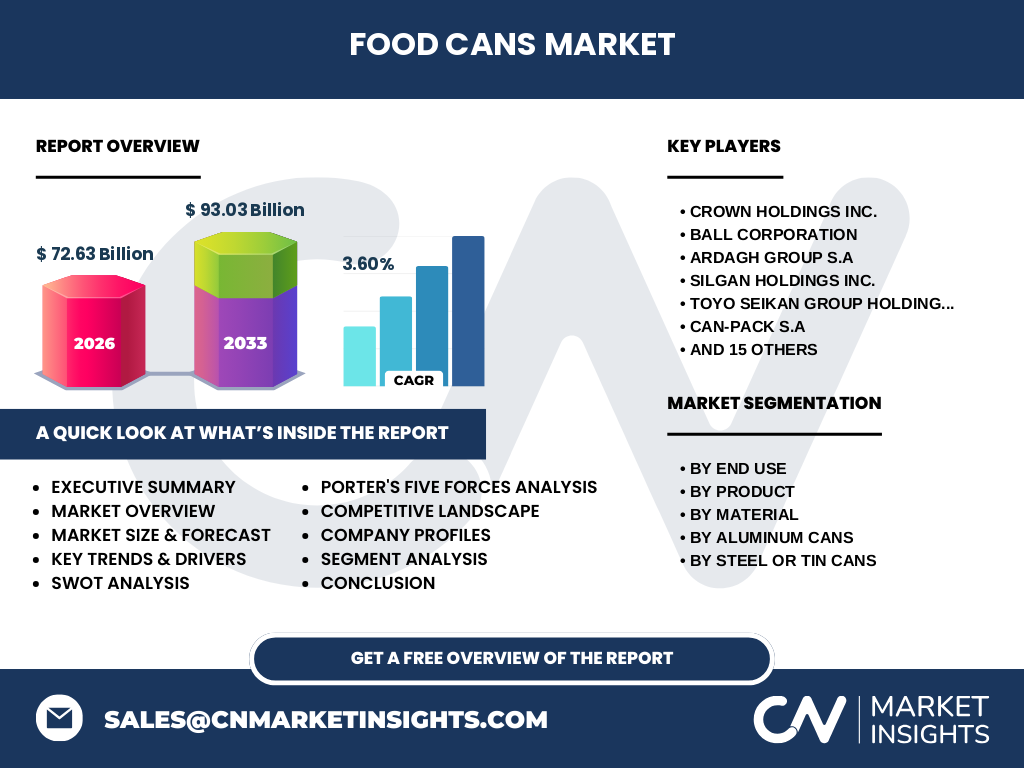
Market overview — definition, scope, and industry significance of Food Cans Market
Our analysis indicates the Food Cans Market represents a vital segment of rigid metal packaging, valued at $72.63 Billion in 2026. This sector encompasses steel, tin, and aluminum containers utilized globally by processors of meat, seafood, sauces, and produce to ensure long shelf life and barrier protection against microbial contamination.
Structural Growth Drivers
Growth in the Food Cans Market is propelled by surging demand for shelf-stable convenience foods and rigorous hygiene mandates enforced by bodies like the FDA. Rising urbanization and busy lifestyles favor lightweight 2-piece cans and easy-open aluminum cans, reducing supply chain friction for perishable goods like fruits and vegetables.
Emerging Trends in Packaging Innovation
The Food Cans Market industry trends highlight a definitive pivot toward sustainability and lightweighting. Producers are adopting advanced coatings for tin-plated steel cans and enameled steel cans to prevent corrosion while meeting stringent environmental regulations set by the European Union regarding packaging waste and recyclability.
How COVID-19 Reshaped Supply Chains
During the pandemic, the Food Cans Market experienced unprecedented spikes in retail demand for non-perishable goods, straining raw material procurement for aluminum and steel. Despite logistical bottlenecks at major global ports, leading manufacturers accelerated automation, ensuring a robust post-pandemic recovery trajectory toward projected 2033 valuations.
Competitive Benchmarking and Market Concentration
The Food Cans Market analysis reveals a consolidated landscape dominated by multinational giants like Crown Holdings Inc., Ball Corporation, and Ardagh Group S.A. These industry leaders leverage vast manufacturing footprints and proprietary alloy technologies to maintain pricing power against regional competitors such as Can-Pack S.A. and Silgan Holdings Inc.
Executive Summary
Our research confirms the Food Cans Market market size stands at $72.63 Billion in 2026, advancing at a steady 3.60% CAGR to reach $93.03 Billion by 2033. This expansion is underpinned by sustained consumer preference for metal packaging over flexible plastics due to superior recyclability and barrier integrity.
Market Forecast from 2027 to 2033
Based on our econometric modeling, the Food Cans Market will expand from its 2026 baseline of $72.63 Billion to $93.03 Billion by 2033, registering a 3.60% CAGR. This steady trajectory reflects continuous capital expenditure by firms like Toyo Seikan Group Holdings Ltd and Sonoco Products Company in high-speed manufacturing lines.
Segmentation Analysis by End Use and Product
The Food Cans Market is segmented by end-use into meat, poultry and seafood, sauces, jams and pickles, and fruits and vegetables. Product lines divide into 2-piece cans and 3-piece cans, utilizing aluminum cans and steel or tin cans like tin-plated steel cans to address distinct thermal processing requirements.
Geographic Distribution and Regional Performance
Regional performance in the Food Cans Market varies significantly, with North America and Europe prioritizing lightweight standard aluminum food cans and eco-friendly coatings. Meanwhile, Asia-Pacific exhibits the fastest growth rate, driven by expanding middle-class populations in emerging economies consuming processed meats, poultry, and canned seafood.
In-Depth Regional Review
Asia-Pacific dominates volume consumption within the Food Cans Market, supported by heavy investments from localized players like CPMC Holdings Limited and Kian Joo Can Factory Berhad. Concurrently, European markets enforce rigorous circular economy directives, pushing manufacturers toward infinitely recyclable steel and aluminum substrate innovations.
Strategic Positioning of Leading Companies
Industry stalwarts like Ball Corporation and Crown Holdings Inc. focus on sustainability-driven product differentiation within the Food Cans Market. Regional players such as Visy Industries, Nampak Products Ltd, and Independent Can Company secure regional market share by tailoring their enameled steel cans to local agricultural harvest cycles.
Porter's Five Forces Analysis
In the Food Cans Market, supplier power remains moderate due to consolidated primary aluminum and steel mills. Buyer power is counterbalanced by high switching costs for specialized food retorting lines, while threat of substitution from flexible pouches is mitigated by metal's unmatched barrier protection and structural rigidity.
SWOT Analysis of the Sector
Strengths of the Food Cans Market include superior recyclability and shelf-life extension. Weaknesses involve raw material price volatility for tinplate. Opportunities lie in emerging pouch-to-can conversions for pet food and sauces, while threats stem from stringent environmental packaging taxes levied across various global jurisdictions.
Value Chain Analysis
The Food Cans Market value chain starts with bauxite mining and steel rolling, progressing to precision body-making and lithographic printing by firms like Metal Container Corporation and Ton Yi Industrial. Finished containers are then supplied to food processors before reaching retail distribution networks worldwide.
Investment Insights and Strategic Recommendations
Investors eyeing the Food Cans Market should target emerging economies where cold-chain infrastructure gaps amplify the need for shelf-stable metal packaging. Strategic partnerships with innovators specializing in BPA-non-intent (BPA-NI) interior coatings offer high potential for capturing premium market share.
Conclusion and Key Takeaways
The Food Cans Market demonstrates robust fundamentals, projected to expand from $72.63 Billion in 2026 to $93.03 Billion by 2033 at a 3.60% CAGR. Companies embracing sustainable manufacturing and advanced lightweighting will capture disproportionate growth in this evolving packaging landscape.
Research Methodology
Our findings on the Food Cans Market are triangulated using a rigorous methodology combining primary stakeholder interviews with packaging executives, trade registry import-export data from major maritime ports, and secondary macroeconomic indicators regarding global processed food production and metal commodities pricing.
Scope of the Report
This comprehensive report evaluates the global Food Cans Market across specific material types, product formats, and end-use verticals. Geographic coverage spans North America, Europe, Asia-Pacific, and LAMEA, with quantitative forecasts bounded between the baseline year 2026 and the terminal forecast year 2033.
Recent Industry Developments
Recent strategic moves in the Food Cans Market feature capacity expansions by Sonoco Products Company and collaborative recycling initiatives by Ardagh Group S.A. Furthermore, regional operators like Thai Can Manufacturing Co. Ltd and Allstate Can Corporation have invested in high-speed digital printing lines to meet localized branding demands.